The day a tree punches through your roof, a pipe bursts over your kitchen, or a wildfire sends smoke into every room, you do not get the luxury of thinking straight. Most homeowners file the claim, take the first number their insurer offers, and accept that whatever the adjuster said is what the damage is worth. That is exactly how insurers want the conversation to go, and how people routinely leave five-figure sums on the table. A home insurance claim is a negotiation, and the other side does it for a living.
The first 48 hours decide everything
Insurance carriers reward organized claimants and punish the rest. The actions you take in the first two days after a loss shape what the claim is worth months later, because every piece of evidence you generate early is harder to dispute. If you only do one thing, do these four:
- Stop the damage from getting worse. Tarps, board-ups, shutting water at the main, removing soaked carpet before mold sets in. Every reasonable mitigation step is reimbursable under virtually every homeowners policy, but only if it is documented.
- Photograph and video everything before you touch it. Wide shots, close-ups, the date stamp showing on your phone. Then photograph the mitigation work as you do it.
- Keep every receipt from minute one. Tarps, fans, dehumidifier rentals, the motel you stayed in, the mileage to the hardware store, takeout because your kitchen is gone. Insurers owe you “additional living expenses,” and receipts are the only way to claim them.
- Call your broker or agent, not the 1-800 number. Independent agents can flag you as a priority, walk you through your specific policy wording, and tell you whether the company is known to play hardball on your kind of loss.
Do not throw anything away yet, even if it looks ruined. A soaked sectional might be a $6,000 line item; the adjuster has to see it. Photograph it where it sits, then set it aside.
What the adjuster will not tell you at the walkthrough
The adjuster who shows up at your house works for the insurance company, not for you. Many are independent contractors paid per claim, and their compensation is usually tied to keeping payouts low. Knowing that changes how you behave on the walkthrough.
Three patterns show up again and again. First, the adjuster starts at the most obvious damage, glances at it, and moves quickly. That pace is a tactic. Slow them down. Walk them through every room, closet, and soft spot in the ceiling. Open drawers and cabinets yourself so they see water lines inside. Second, they often skip the attic, crawlspace, or HVAC ducts because those are where mold, structural, and air-quality claims live, and where the real money is. Insist on those inspections and request they be in writing. Third, they almost always write up the estimate with cheap labor and the cheapest materials. Demand a copy of the estimating software (Xactimate is the industry standard) and the line items. If your zip code’s labor rate is wrong or your roof’s “like kind and quality” is being priced as builder-grade when you have architectural shingles, that is recoverable.
Do not sign anything at the walkthrough. Do not give a recorded statement on the spot. You are allowed to take a day to think.
The documentation stack that wins disputes
The single biggest predictor of claim size is the documentation the policyholder brings to the fight. Insurers deny or lowball claims because the file does not justify a higher number. Build your file as if you are preparing a lawsuit, because sometimes you will be.
- A written timeline with dates, times, weather data (NOAA storm reports, USGS earthquake data, local fire department incident numbers), and who you spoke with at the insurer.
- Contractor estimates from at least two licensed and insured contractors, ideally one the insurer has not pre-approved. Carriers maintain preferred-contractor networks because those vendors agree to insurer pricing. An independent contractor’s estimate is your leverage.
- Contents inventory with photos, model numbers, and approximate replacement costs. If you cannot remember everything, scroll back through your phone photos, online orders, and credit card statements. People forget 40% of what they own.
- The full policy, declarations page, and any endorsements. Read the “Loss Settlement” section. If you have an “RCV” (replacement cost value) policy, the insurer owes you what it costs to replace today, not what your five-year-old roof was worth yesterday. If you only have “ACV” (actual cash value), they owe depreciation plus replacement cost once you finish the work.
- All written communication with the insurer. If it is not in writing, it did not happen. After every phone call, follow up with an email: “Confirming our call today at 3pm where we discussed X, and you committed to Y by Friday.”
When the first offer is a lowball
Expect a lowball. On a $50,000 roof and interior claim, an initial offer of $18,000 to $28,000 is normal. That is not the end of the negotiation, it is the opening. Three moves almost always work:
File a formal written supplement through your contractor, line by line, with photos and pricing backed by the Xactimate database for your area. Insurers settle supplements quickly when itemized this way. Second, invoke the appraisal clause in your policy. Most homeowners policies include a two-appraiser process where each side hires an appraiser and a neutral umpire settles the disagreement. Carriers back down a lot before this happens because they know they will lose. Third, if the carrier is stonewalling, hire a public adjuster. They are licensed professionals who work for you and typically take 5% to 12% of the final settlement. The math works on any claim over about $25,000, because they usually double what the homeowner would have accepted.
How to push a claim to a real payout
Avoid three traps. Do not accept the first check as a full and final settlement, ever, because once you sign that release you cannot reopen the claim. Do not rebuild before the insurer has agreed in writing to the scope, because if you rebuild first they can argue the damage was cosmetic. Do not lie or invent items; modern claims software flags anomalies, and insurers will deny the whole claim over a single padded number.
The homeowners who get full payouts do five things. They document early, document often, and document in writing. They know the difference between RCV and ACV before the adjuster arrives. They bring independent contractor estimates, not just the carrier’s favorite vendor. They use the appraisal clause or a public adjuster when the company stalls. And they keep every email, photo, and receipt until the final check clears and the work is done. Your insurer is a business that profits by paying you less than your policy says it owes. The policy is the contract. The documentation is the proof.
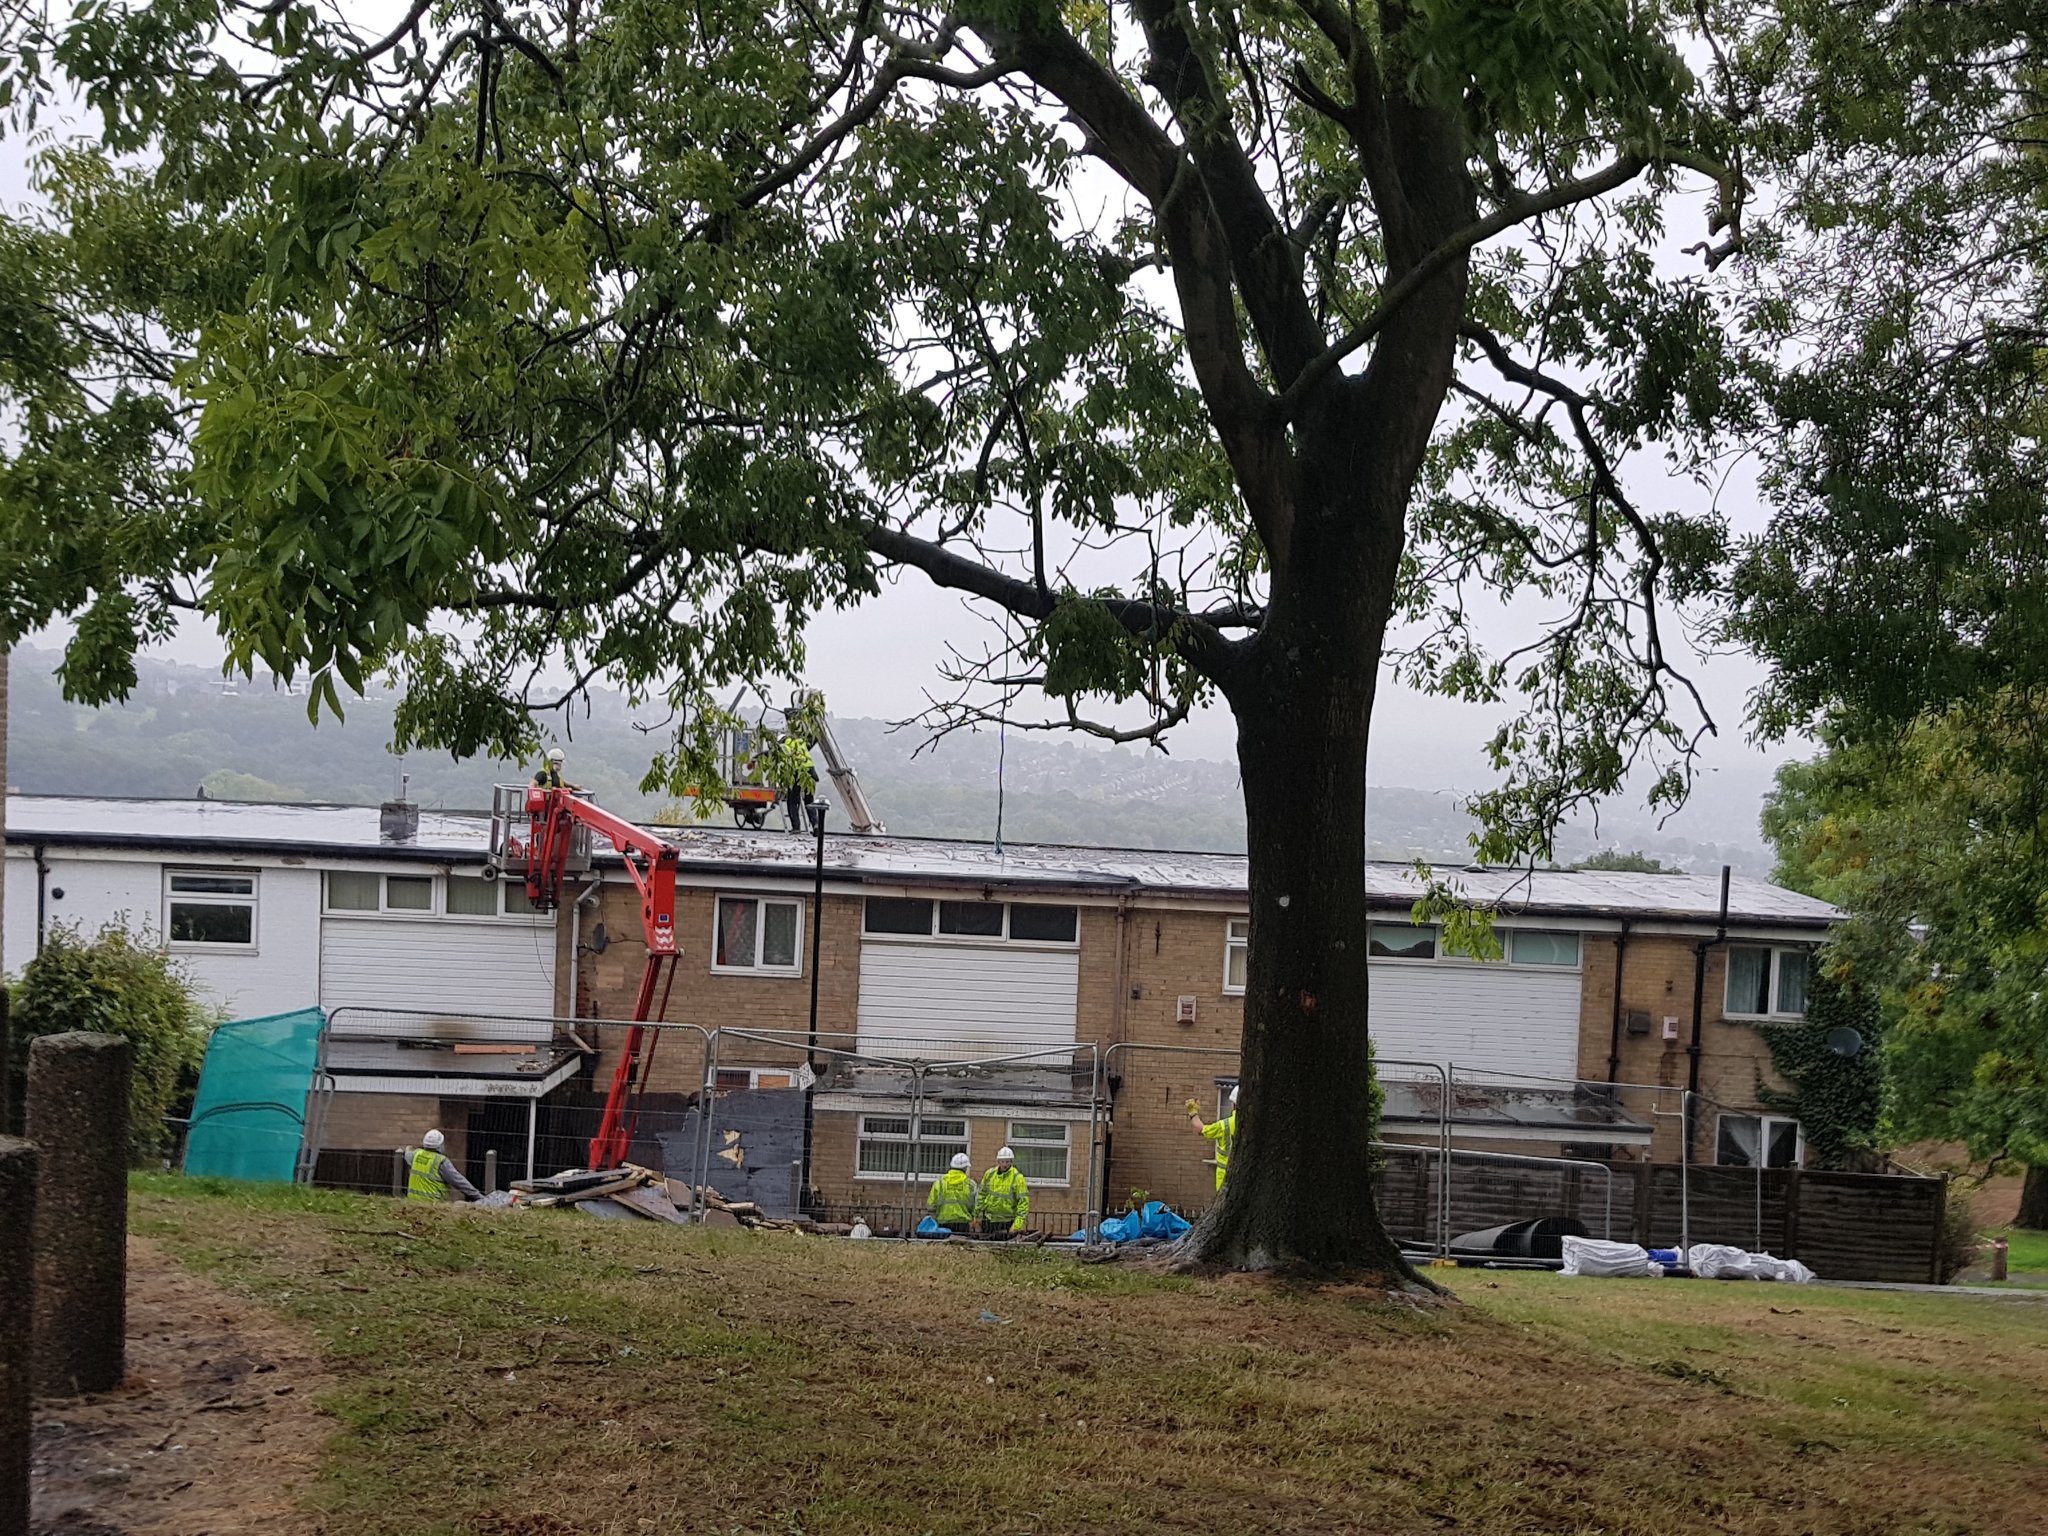
Image: Buttons0603, Wikimedia Commons (CC BY-SA 4.0) — repairs to a roof-damaged house in Sheffield, UK, after Storm Ali, 2018.