The First Ten Minutes Decide Everything
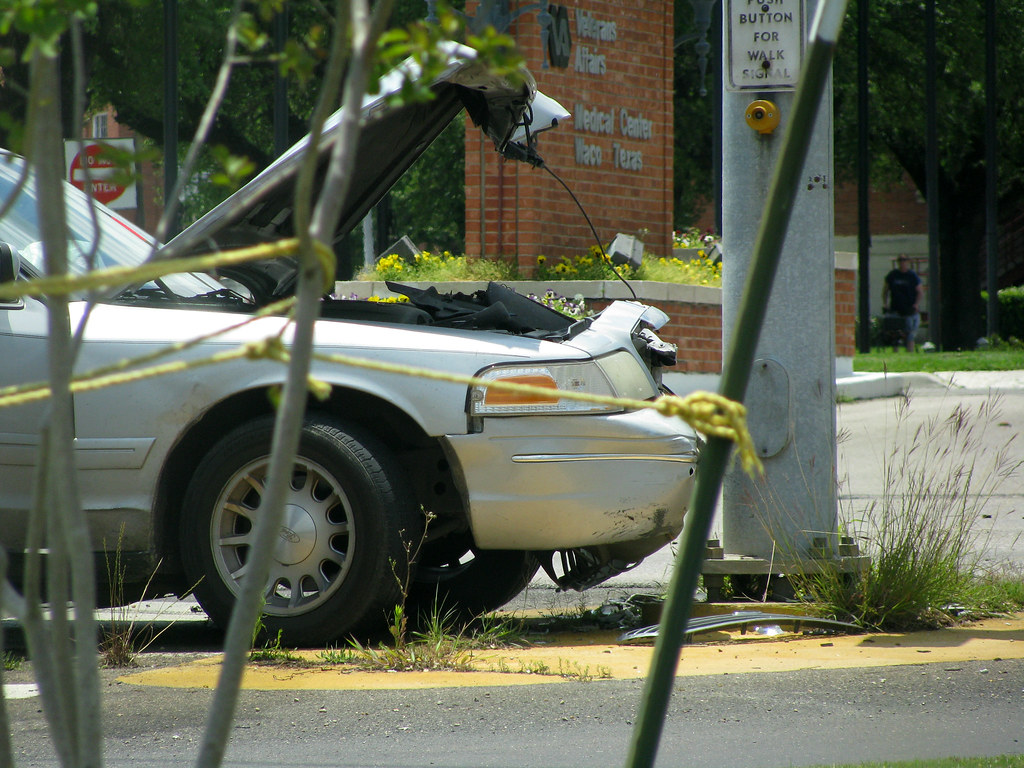
You didn’t cause the crash. The other driver ran the light, blew the stop sign, or pulled out of a parking spot without looking. The first instinct is to argue, to prove it, to make the wrong party understand. Don’t. The ten minutes after impact quietly decide whether you walk away financially whole or spend the next two years fighting an insurance company that has decided you are at least 31% responsible.
Pull out of the travel lane if you can do it safely. Turn on your hazards. Check yourself and your passengers before you start making calls. Then call the police. Not “if it’s serious.” Call it every time the damage looks like more than a parking-lot bump, because a police report is the single piece of paper that shifts the entire claim in your favor. Without one, the other driver’s insurer will treat your account as 50/50 hearsay, and you’ll be paying for repairs you didn’t cause.
Document Everything Before Anyone Moves the Cars
Once everyone is safe and help is on the way, start documenting. Most people take three or four photos from chest height, three feet back, and call it good. That’s not enough. Walk the scene like an insurance adjuster would:
- Wide shots of all four corners of each vehicle, with the other vehicle’s plate visible.
- Close-ups of every damaged panel, even the ones that look minor. New damage gets fixed; old damage gets blamed on you.
- The other driver’s license plate, the street signs, the direction of travel, the position of the sun, and any skid marks or debris patterns on the road.
- The license, registration, and insurance card of the other driver. Photograph them; don’t just write down the policy number.
- The names and phone numbers of any witnesses. Witnesses disappear within an hour, and the adjuster will be calling them on Thursday.
- A short voice memo on your phone describing what happened in your own words while it’s still fresh. Memory edits itself after 24 hours.
Do not, under any circumstances, say “I’m sorry” or “I didn’t see you either” to the other driver. Apology is an admission in the eyes of every claims department in America. Sympathize with their bad day, exchange information, and let the documentation do the talking.
The Other Driver’s Insurance Will Sound Reasonable. They Aren’t.
The at-fault driver’s adjuster will call you within 48 hours, often within 12. They will sound sympathetic. They will offer to “just handle this directly” so you don’t have to “go through insurance” and your rates don’t go up. What they want is a recorded yes on a recorded line that locks in their version of events before you’ve talked to anyone who actually works for you.
Don’t give a recorded statement on day two. Tell them you will call them back after you’ve spoken with your own insurer, then call your insurer first. Your collision coverage will pay for your repairs now and pursue the at-fault carrier through subrogation. You will not be penalized for using your own coverage when you weren’t at fault — your insurer recovers the money from the other side and your premium doesn’t move.
When you do call them back, stick to facts. Where, when, direction of travel, what you saw. Do not speculate about speed, do not characterize the other driver’s intent, and do not accept any settlement offer before the medical review window has closed. Soft-tissue injuries show up three to seven days later. If you’ve signed a release on day three, you’ve waived the right to claim the back injury that woke you up on day six.
The Three Claims Most People Don’t Know They Can Make
Once the basics are settled, there are three underused claims that turn a bad day into a fully compensated one.
Diminished value. Your car is repaired and looks new. The dealer knows it isn’t. A vehicle with a significant accident on the Carfax is worth 10–25% less than an identical one without one, and that loss is the at-fault driver’s responsibility in most states. File a separate diminished-value claim against their insurer after the repair is complete; if they lowball you, hire an independent appraiser for $300 and send the report with your counteroffer. The number usually moves within 48 hours.
Loss of use. If your car is in the shop for ten days, you’re entitled to a rental or the cash equivalent for the entire repair period — including the days the shop was waiting on parts they didn’t order until you called. Track every delay. Adjusters pad the rental authorization by exactly one day under the original estimate; if the shop needed twelve and you were authorized for six, you can recover the gap.
Towing and storage. If the car was towed, storage fees start accruing immediately, sometimes $50–$100 per day. Get it out as fast as you can once it’s released by police, and submit the tow and storage invoices to the at-fault carrier. Many shops will store a car for free for 24–48 hours if you ask. Few people ask.
When to Stop Handling It Yourself
If anyone is injured, if the other driver disputes fault, if the damage exceeds roughly $5,000, or if the at-fault carrier is delaying beyond three weeks without a written offer, the math changes. A personal-injury or property-damage attorney will take most not-at-fault cases on contingency, meaning they only get paid if they win. The standard contingency fee is one-third of the recovery, but the at-fault carrier’s offer typically jumps by a factor of three to five once they see a lawyer’s letterhead, because the cost of litigating now exceeds the cost of settling.
The mistake most drivers make is waiting too long to escalate. By month four, the medical records are scattered, the witness has stopped returning calls, and the adjuster has built a file that frames you as 30% at fault. By month eight, your case is worth half what it was on day one. The moment you can feel the other carrier dragging its feet, that is the cheapest moment to hand the file to a lawyer.
None of this is about gaming the system. It’s about not subsidizing the at-fault driver’s insurer when you’ve done nothing wrong. The other carrier has a claims playbook, and you have ten minutes of adrenaline and a phone with 4% battery. The moves above are how you level that field.